Crypto news report · source clearly identified
Self‑custody of Bitcoin can leave a cost‑basis gap on 2026 US tax forms
Under the 2026 IRS rules, Bitcoin moved out of an exchange and back into the same account is treated as non‑covered, so brokers may report sale proceeds without mandatory acquisition‑cost information, creating a blind spot for investors.
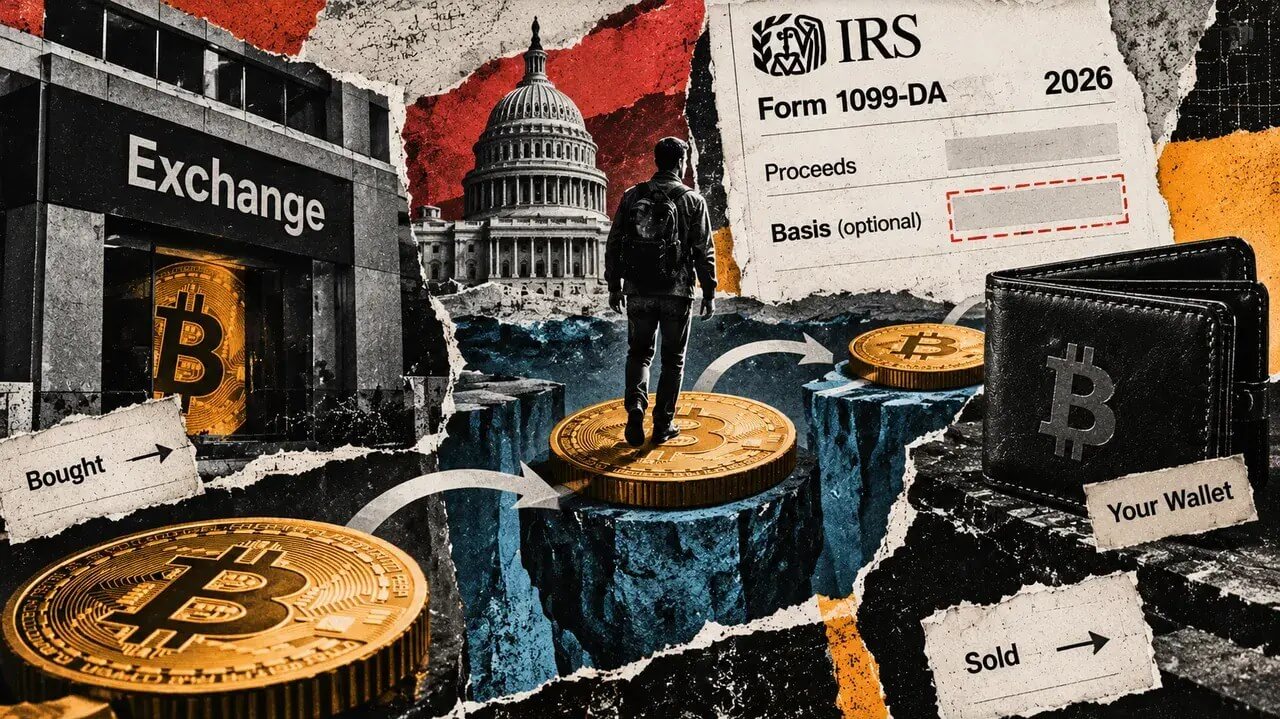
For the 2026 tax year, the IRS distinguishes between “covered” and “non‑covered” digital assets when requiring brokers to report cost basis. A Bitcoin that is withdrawn from an exchange, held in a personal wallet, and then returned to the same exchange does not meet the continuous‑custody condition, meaning the broker’s Form 1099‑DA will report the sale proceeds but not the acquisition cost.
How the reporting classification works
Covered assets are those acquired after 2025 and held in the reporting broker’s custodial account until disposal. For these assets, brokers must report both proceeds and basis. Assets bought before 2026 or transferred into the broker are classified as non‑covered, and basis reporting is voluntary.
Three custody scenarios – same gain, different reporting
- Continuous custody with the selling broker (covered): mandatory basis reporting ($5,000) and $2,000 gain.
- Purchase with one broker, transfer to another before sale (non‑covered): basis reporting voluntary ($5,000) and $2,000 gain.
- Purchase, withdraw to personal wallet, return and sell (non‑covered): basis reporting voluntary ($5,000) and $2,000 gain.
Only the third path is easy to overlook because the return to the original account does not satisfy the continuous‑custody rule.
Guidance from major exchanges
Coinbase notes that its 2025 forms reported only proceeds, with basis information beginning in 2026 for certain assets, and advises users to keep records from other wallets. Kraken’s 2025 combined forms show estimated basis for internal activity but report only gross proceeds to the IRS; returning assets are treated as new deposits without automatically restoring prior basis.
International reporting and analytics
The OECD’s Crypto‑Asset Reporting Framework (CARF) will exchange transaction data between jurisdictions but does not replace the US Form 1099‑DA. Chainalysis estimates over $457 billion of potentially taxable on‑chain activity in 2025, including $112.6 billion linked to the United States, highlighting the scale of activity that may lack acquisition‑cost data.
What investors need to do
To calculate gains accurately, investors must retain their own acquisition records and connect the original purchase to the eventual sale, regardless of broker‑reported basis. Specific identification rules require timely identification of units when using a broker’s designated identifiers.
Source & attribution
News Source
- Publisher
- CryptoSlate
- Original date
- September 15, 2026, 8:40 AM
- Original headline
- Bitcoin self-custody creates a massive cost-basis blind spot on your 2026 crypto tax forms