Crypto news report · source clearly identified
SEC Commissioner Hester Peirce Says Truly Decentralized DeFi Needs No Legal Exemption
SEC and CFTC actions focus on custody, access, routing, fees and intervention powers, each within a separate legal framework.
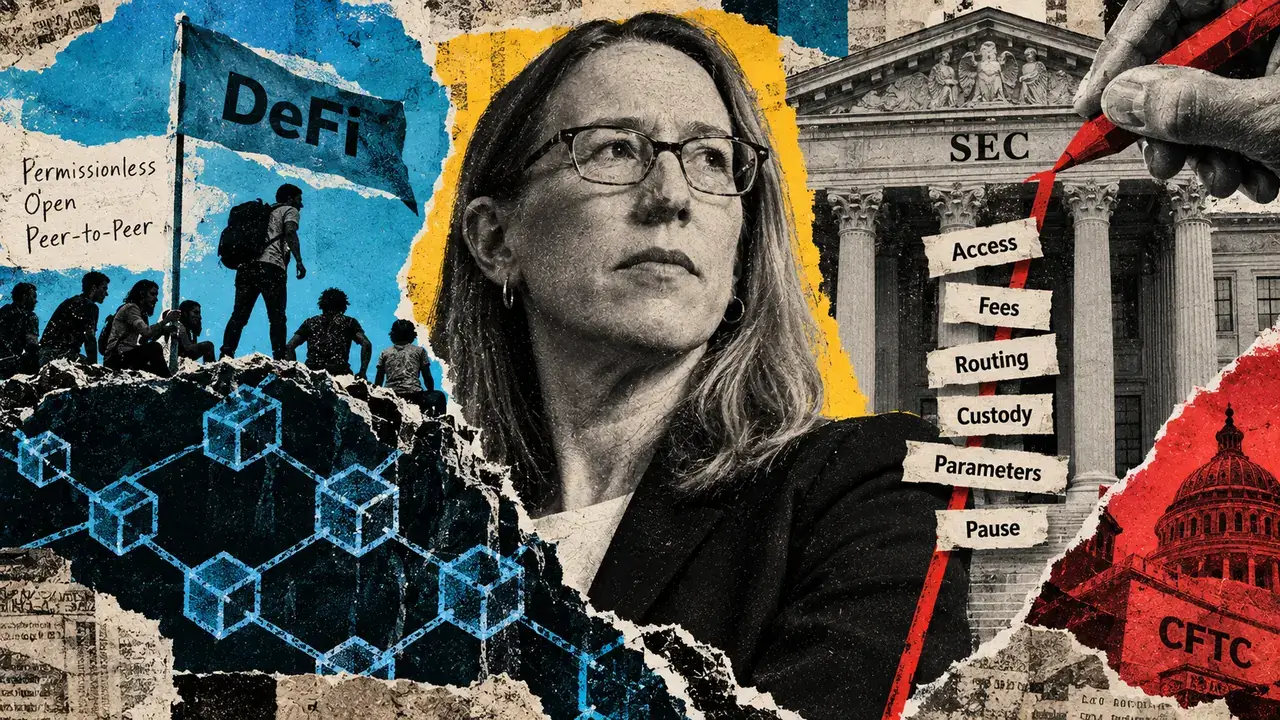
SEC Commissioner Hester Peirce stated on September 17 that investors do not need a regulatory exemption to use permission‑less smart contracts for peer‑to‑peer trading. Her comment highlights the regulatory uncertainty surrounding how much control a software provider can retain before being treated as a regulated intermediary.
SEC Tokenized‑Securities Order
The SEC issued a temporary, conditional relief order for a Tokenized Securities Venue (TSV). The order permits automated market‑maker pools for permissioned trading of tokenized NMS stocks and sets standards for who may access those pools. Actions such as selecting a pool, deploying its contract, changing parameters, setting fees, or retaining the ability to pause trading are considered “providing” the venue. Purely administrative tasks, like encoding a whitelist, are not.
SEC Staff Position on Crypto Interfaces
An April staff statement from the SEC’s Division of Trading and Markets outlines when the agency would refrain from objecting to crypto‑asset securities interface providers that operate without broker‑dealer registration under Section 15. The statement is non‑binding, will expire five years after April 13, 2026, and applies only if the provider:
- Allows users to hold their own keys and sign transactions.
- Displays multiple execution routes that are filterable or sortable using objective criteria.
- Charges a flat or percentage fee that is objectively determined, consistently applied, and neutral across products, routes, venues and counterparties.
The staff position excludes providers that hold or access user assets, solicit specific transactions, give investment recommendations, execute or settle trades, or take discretionary routing actions.
CFTC No‑Action Position
The CFTC’s Market Participants Division issued a no‑action letter (Staff Letter 26‑25) on September 17. It states that the agency will not recommend enforcement against passive‑software providers that fail to register as introducing brokers, provided the following conditions are met:
- Users transact directly on a designated contract market or through a registered futures commission merchant or introducing broker.
- The provider does not custody user assets, give explicit buy or sell signals, or exercise discretion over order routing or execution.
- The provider may promote specific derivatives, direct users to registered firms, charge transaction‑based fees, and share revenue with a registrant, as long as the provider remains hands‑off.
The CFTC position allows broader promotional activities and revenue‑sharing arrangements than the SEC’s interface stance, but still requires clear separation from customer property and discretionary control.
Key Areas of Control Compared
The SEC order, SEC staff position, and CFTC staff position each draw lines around six forms of control:
- Custody: Both agencies bar the provider from holding or accessing user assets.
- Access: The SEC’s TSV sets participant standards; the CFTC requires direct user access to the registered market.
- Recommendations: The SEC excludes specific transaction solicitation; the CFTC permits promotion but bans explicit buy/sell signals.
- Routing: The SEC bars order taking or routing; the CFTC bars discretionary routing.
- Fees: The SEC allows neutral, objectively determined fees; the CFTC permits transaction‑based fees and revenue sharing.
- Parameters and Pauses: Changing pool rules, fees, or pausing trading can be viewed as providing the venue under the SEC order.
What “Truly Decentralized” Means for Regulators
Peirce’s statement reflects a principle that removing a trusted intermediary weakens the regulatory rationale for treating a platform as a broker or exchange. However, her comment does not create a binding legal definition. The SEC and CFTC each apply their own statutory frameworks to specific facts, resulting in a fragmented regulatory landscape without a unified “decentralization test.”
Source & attribution
News Source
- Publisher
- CryptoSlate
- Original date
- September 21, 2026, 2:35 PM
- Original headline
- Why truly decentralized DeFi needs no legal exemption according to SEC Commissioner Hester Peirce